A buyback-and-disposal drive run by investment adviser Gravis has pulled GCP Infrastructure's shares back towards net asset value, with the discount shrinking from almost 45% to 14% in under three years.
GCP Infrastructure Investments Limited (LSE: GCP) has narrowed the gap between its share price and net asset value to around 14%, down from a discount of nearly 45% in October 2023, as a sustained campaign of disposals and buybacks engineered by investment adviser Gravis Capital Management gains traction.
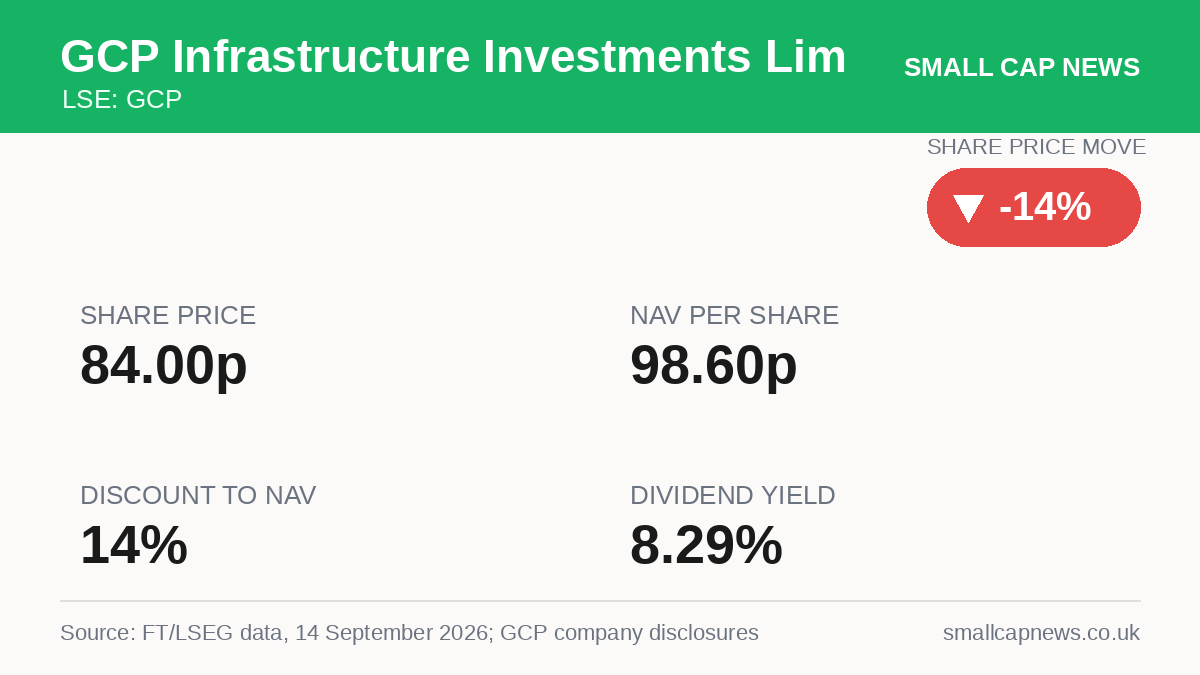
Shares in the infrastructure debt specialist closed at 84.00p on 14 September 2026 against a NAV of 98.60p, according to Financial Times data supplied by LSEG, with the stock also carrying a dividend yield of 8.29%. The narrowing discount reflects a deliberate strategy rather than a market re-rating alone: Gravis has been selling assets, repaying debt and funnelling proceeds into share buybacks since the board adopted a formal capital allocation policy in December 2023.
That policy was designed explicitly to address what the board called 'the disconnect between share price and NAV', targeting £150 million of capital returns through accelerated disposals, debt reduction, buybacks and a rebalancing away from sectors such as supported living and equity-like renewables exposure. At February 2026's Capital Markets Day, the framework was sharpened further: below a 15% discount to NAV, the company will again start weighing new investment opportunities alongside continued shareholder returns, a threshold GCP's shares now sit within.
The scale of the buyback effort has been significant. In the quarter to 30 June 2026 alone, GCP repurchased more than 19 million shares, adding 0.57 pence per share to NAV, while since the programme's 2023 inception it has bought back over 125 million shares for total consideration of roughly £98 million. Management argues that buying stock back at a discount is inherently value-accretive for remaining holders, and a series of summer disposals and refinancings struck at or above book value has reinforced the case that GCP's published NAV is not overstated.
None of this guarantees the discount keeps closing, and the board has acknowledged that wider market sentiment can move against even well-executed capital allocation. But with a fully repaid credit facility, an active buyback authority renewed at the 12 February 2026 AGM, and a discount now inside the 15% trigger point, attention turns to whether GCP starts redeploying capital into new infrastructure assets alongside its ongoing returns to shareholders.
This report is based on GCP Infrastructure Investments Limited’s announcement and coverage by UK Investor Magazine. Company announcements can be tracked via London Stock Exchange RNS and Investegate, and the full results calendar is worth watching for the next update.
This article is for general information only and does not constitute investment advice or a recommendation to buy or sell any security. Photo: Chris Briggs on Unsplash.
Small Cap News covers London’s junior market – AIM, small-cap and growth companies – with concise, sourced reporting on the results, deals and regulatory news that move share prices. We track the stories private investors actually need, from contract wins and drilling updates to fundraises and half-year figures, straight from the market’s own announcements.