Four months of contract wins have taken Physiomics close to a full year's revenue, but turning bookings into profit is the next hurdle.
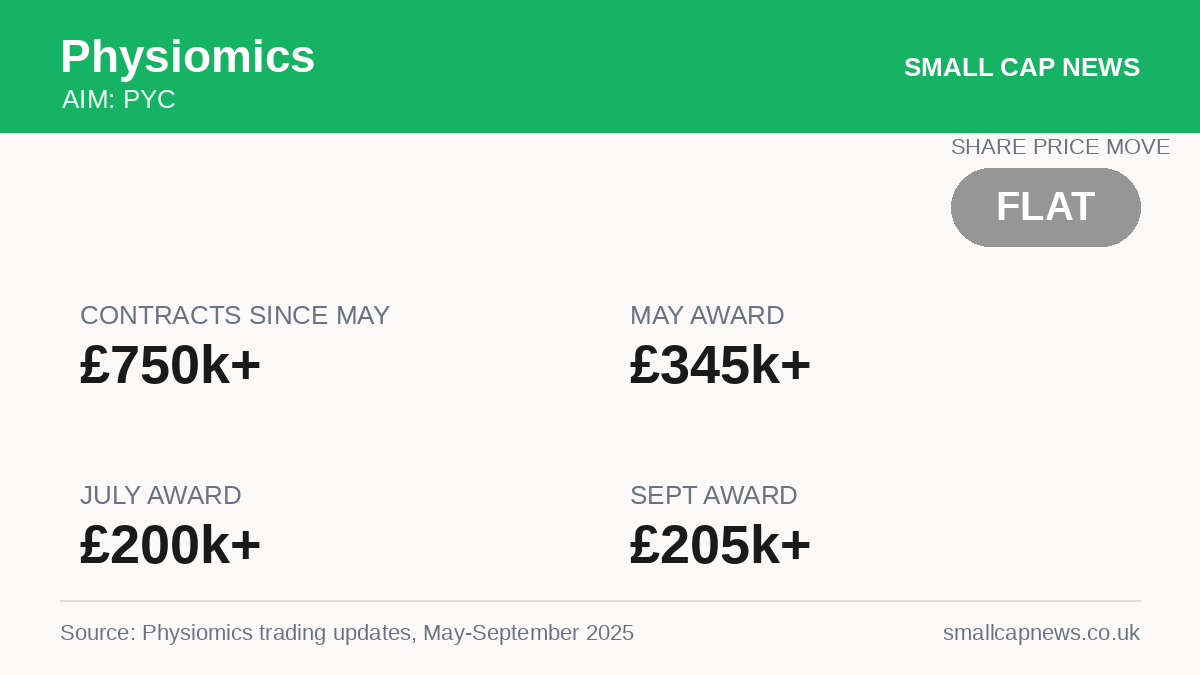
Physiomics (AIM: PYC) has announced more than £750,000 worth of new contracts since May, a sum the modelling and simulation specialist says equates to roughly 95% of its entire revenue for the 2024 to 2025 financial year. The source article does not report any accompanying share price movement, so this piece focuses on the operational and commercial detail rather than a trading reaction.
The run of awards follows a shareholder-driven shake-up of the board in April, after which management carried out a strategic and operational reset aimed at sharpening commercial focus and pushing the business towards break-even. That reset appears to be bearing fruit: May brought over £345,000 of new work across modelling, simulation, biometrics and data science, July added a further £200,000-plus including a new contract with a Boston-based cancer immunotherapy biotech, and September contributed another £205,000, building a steady drumbeat of announcements rather than a single large deal.
What stands out is the spread of work across service lines and clients rather than reliance on one customer or product, something management and outside observers both point to as evidence of genuine commercial traction rather than a one-off spike. Physiomics also flagged rising interest in its specialist modelling capabilities from international research and clinical collaborators, suggesting the pipeline could widen further.
Contract value is not the same as recognised revenue, however, since projects can span several months or roll into future financial years, and gross margins on that work have not yet been disclosed. The company's own framing of the £750,000 figure against last year's full-year revenue gives a useful yardstick for momentum, but it does not confirm improved profitability or cash generation on its own.
Attention now turns to Physiomics' next set of financial results, which should show how much of this contract momentum has actually converted into booked revenue and whether the cost savings identified alongside the commercial reset are holding. Repeat business from existing clients and progress towards the stated break-even target will be the markers investors watch most closely, rather than further headline contract wins in isolation.
This report is based on Physiomics’s announcement and coverage by Share Talk. Company announcements can be tracked via London Stock Exchange RNS and Investegate, and the full results calendar is worth watching for the next update.
This article is for general information only and does not constitute investment advice or a recommendation to buy or sell any security. Photo: Chidera Faustina Okeke on Unsplash.
Small Cap News covers London’s junior market – AIM, small-cap and growth companies – with concise, sourced reporting on the results, deals and regulatory news that move share prices. We track the stories private investors actually need, from contract wins and drilling updates to fundraises and half-year figures, straight from the market’s own announcements.