JP Morgan turns bullish on the Bitcoin-miner-turned-AI-cloud operator, betting on soaring compute pricing and a Microsoft-anchored contract book.
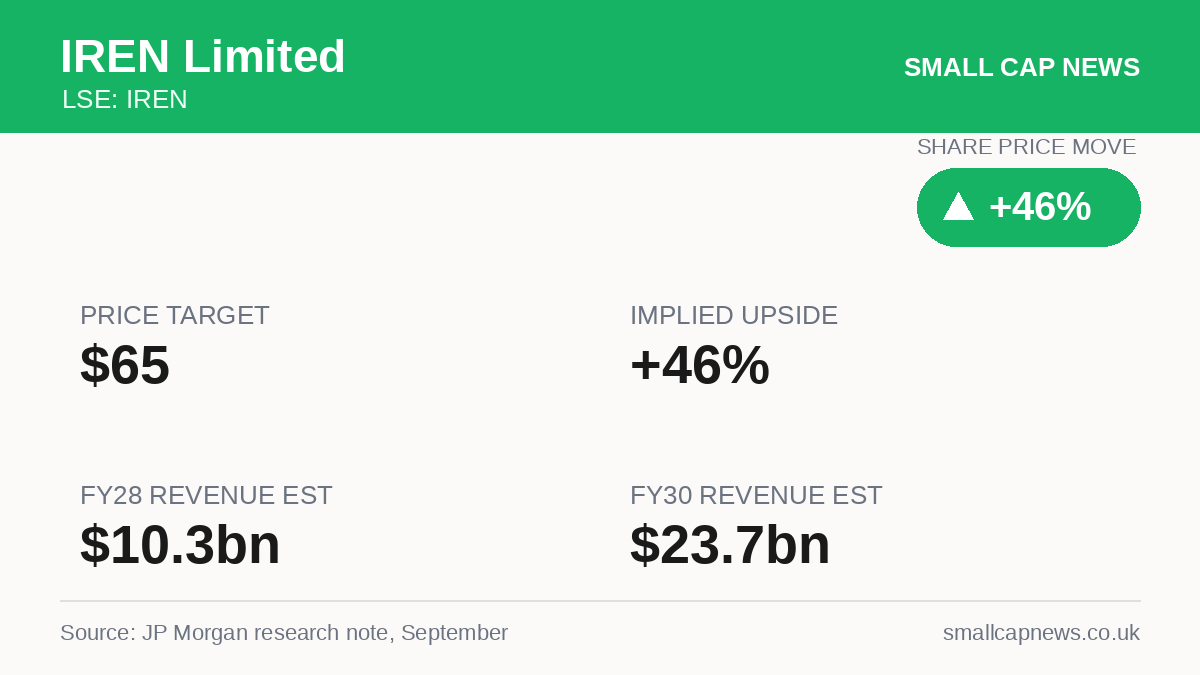
JP Morgan has thrown its weight behind IREN (LSE: IREN), forecasting the AI infrastructure group's revenue could balloon roughly 20-fold by 2030 as demand for high-powered computing capacity outstrips supply. The bank upgraded the stock to 'Overweight' from 'Underweight' and lifted its price target to $65 from $46, implying around 46% upside from IREN's current $44 share price.
The upgrade rests on JP Morgan's view that IREN has evolved into a top-tier 'neocloud' provider, riding a wave of deal momentum and sharply rising prices for AI computing capacity. The bank's model points to FY28 revenue more than doubling to $10.3bn from $4.8bn, with adjusted EBITDA climbing to $6.8bn from $3.4bn, before revenue reaches $23.7bn and EBITDA hits $15.4bn by FY30, with margins holding near 65%.
Capacity growth underpins the thesis. IREN finished June with 40MW of IT capacity generating $1bn of operating annualised revenue, but JP Morgan expects around 400MW live by the end of calendar 2026, supporting roughly $4bn of ARR, rising towards $4.7bn once Nvidia-linked deployments begin in early 2027. The company's contract book is anchored by a five-year, $9.7bn agreement with Microsoft and a $3.4bn deal with Nvidia, alongside customers including Perplexity, Cohere, Figure AI and Together AI.
Pricing dynamics are central to the re-rating: JP Morgan notes neocloud contract rates have moved from $10-15 per watt to $15-20 per watt and beyond, with management reportedly discussing terms closer to $25 per watt for future capacity, potentially making the bank's base-case assumptions conservative.
The bank flags meaningful sensitivity in its numbers. Signing around 450MW of unsigned 2027 capacity at $15 per watt would generate $6.75bn in annual revenue and a $17.5bn net present value, but that falls to $8.75bn at $10 per watt and rises to $26.25bn at $20 per watt. JP Morgan also points to evidence that GPUs may last longer than the five-to-six-year lifespan typically assumed, which could materially improve profitability given depreciation is among the business's largest costs.
This report is based on IREN Limited’s announcement and coverage by UK Investor Magazine. Company announcements can be tracked via London Stock Exchange RNS and Investegate, and the full results calendar is worth watching for the next update.
This article is for general information only and does not constitute investment advice or a recommendation to buy or sell any security. Photo: Taylor Vick on Unsplash.
Small Cap News covers London’s junior market – AIM, small-cap and growth companies – with concise, sourced reporting on the results, deals and regulatory news that move share prices. We track the stories private investors actually need, from contract wins and drilling updates to fundraises and half-year figures, straight from the market’s own announcements.