The professional services and stock-audit specialist heads into Monday's Interims sitting on a five-month rally that has left investors weighing whether to bank profits or hold on.
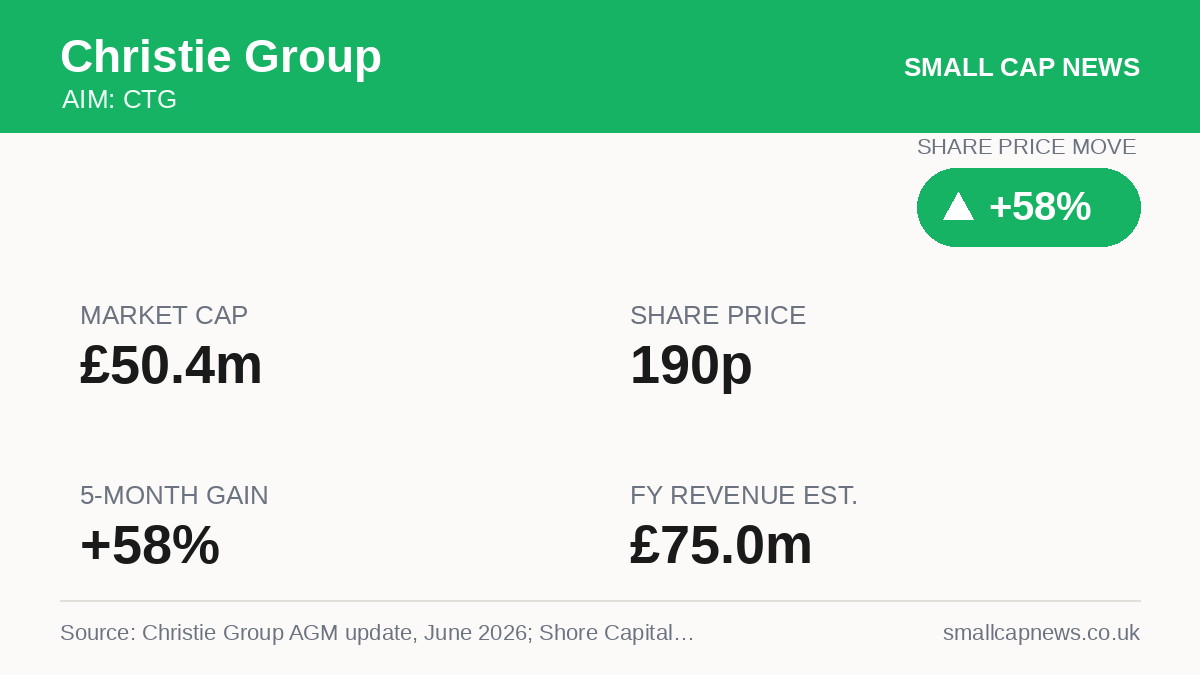
Christie Group (AIM: CTG) will publish half-year results to end-June on Monday, with the shares having climbed to 190p from 120p at the time of a feature on the stock five months ago, a 58% gain, and up 52% since the start of the year, leaving the business services group valued at £50.4m.
The rally has been driven by a robust trading update in June, when the company said it had made a good start to the financial year, with a healthy deal pipeline and demand holding up across its markets, and confirmed that full-year expectations remained unchanged.
Christie Group, which traces its roots back to 1896, operates across 32 offices in the UK and Continental Europe, split into two divisions: Professional & Financial Services, which accounts for 84% of group revenue and covers agency, valuation and advisory work tied to sales and acquisitions of businesses in hospitality, leisure, healthcare, childcare and retail; and Stock & Inventory Systems & Services, the remaining 16%, which provides steadier, cycle-resistant income from stock audit and inventory management. At June's AGM update, the UK agency pipeline was reported up more than 14% in value and 19% in volume year-on-year, valuation and business appraisal revenues rose over 8%, and fee income at Christie Finance jumped 23%, with the group still targeting sales of more than 1,000 businesses this year, weighted towards the second half.
Shore Capital's Rob Sanders regards the shares as significantly undervalued even after the recent run, putting fair value at 250p. He expects group profits to dip this year as the company continues to invest in its UK and European operations to broaden its multi-sector offering, forecasting revenue of £75.0m against £70.6m previously, adjusted pre-tax profit of £4.6m versus £6.0m, earnings of 13.6p against 19.4p, but a higher dividend of 4.5p versus 3.5p. He sees growth resuming thereafter, with revenue of £80.4m and profit of £5.6m in 2027, rising to £86.1m of revenue and £6.6m of profit in 2028, alongside progressive dividend increases to 5.5p and 6.5p respectively. Long-term shareholders remain concentrated, led by the Estate of Philip Gwyn at 27.93%, JP Rugg at 6.00% and Lord Lee of Trafford at 5.88%.
With the shares up 52% this year, some investors may look to lock in gains around the Interims and there is a risk of a short-term dip on any softer-than-hoped detail, but the underlying commentary suggests the growth story remains intact for those prepared to hold through near-term volatility.
This report is based on Christie Group’s announcement and coverage by UK Investor Magazine. Company announcements can be tracked via London Stock Exchange RNS and Investegate, and the full results calendar is worth watching for the next update.
This article is for general information only and does not constitute investment advice or a recommendation to buy or sell any security. Photo: Radission US on Unsplash.
Small Cap News covers London’s junior market – AIM, small-cap and growth companies – with concise, sourced reporting on the results, deals and regulatory news that move share prices. We track the stories private investors actually need, from contract wins and drilling updates to fundraises and half-year figures, straight from the market’s own announcements.