The Dynam Capital-managed trust says Vietnam's top lenders have shifted from a leveraged growth bet to the engine room of the economy itself.
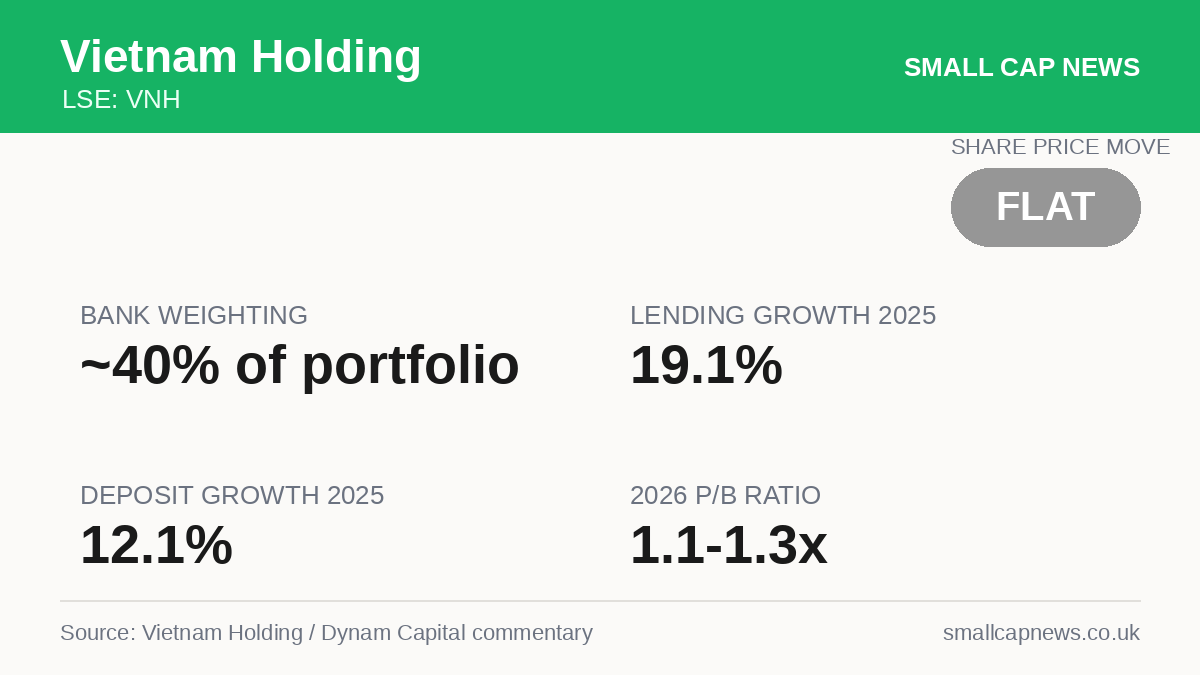
Vietnam Holding (LSE: VNH), the London-listed investment trust run by Dynam Capital, has built almost 40% of its portfolio around Vietnamese banks, arguing the country's leading lenders have evolved from a simple leveraged play on growth into the institutions driving the economy's transformation.
Five banks feature in the trust's top ten holdings, including Techcombank and MB Bank, reflecting a conviction call that has sharpened rather than softened even as credit growth in Vietnam has outpaced deposit growth, leaving a funding gap the trust says demands careful stock selection rather than a broad sector bet.
The trust's thesis has moved on from Vietnam's earlier 'penetration' story, when the priority was simply opening more bank accounts; 89% of Vietnamese adults now hold a payment account, up from around 30% in 2010. The next leg of growth, Vietnam Holding argues, comes from deepening engagement through lending, wealth, insurance and digital products, a shift that plays to well-capitalised banks with sticky, low-cost retail deposits.
Vietnam's government has targeted double-digit GDP growth between 2026 and 2030, backed by an estimated USD1.47 trillion of social investment, with banks expected to fund 40–70% of major infrastructure projects given the country's still-developing capital markets. But lending grew 19.1% in 2025 against deposit growth of 12.1%, and the credit-to-GDP ratio has climbed to 145%, prompting Vietnam Holding to apply seven screens covering funding, capital, returns, asset quality, franchise strength, governance and valuation to narrow its exposure to banks such as MBB, TCB, VPB, HDB and VCB.
On valuation, the trust points to Vietnamese banks trading on a 2026 price-to-book of 1.1–1.3 times against return on equity of 16–18% and five-year EPS growth of 15–20%, with dividend yields of just 2.5–3.5% reflecting a preference for reinvesting capital over paying it out. Regulatory support from the State Bank of Vietnam, including eased liquidity rules and exemptions for infrastructure and social-housing loans, underpins the case, though the widening gap between strong and weak lenders means the trust's active stock-picking approach, rather than broad index exposure, remains central to its pitch to investors.
This report is based on Vietnam Holding’s announcement and coverage by UK Investor Magazine. Company announcements can be tracked via London Stock Exchange RNS and Investegate, and the full results calendar is worth watching for the next update.
This article is for general information only and does not constitute investment advice or a recommendation to buy or sell any security. Photo: Tron Le on Unsplash.
Small Cap News covers London’s junior market – AIM, small-cap and growth companies – with concise, sourced reporting on the results, deals and regulatory news that move share prices. We track the stories private investors actually need, from contract wins and drilling updates to fundraises and half-year figures, straight from the market’s own announcements.