From April 2027 most unused pension pots will be pulled into inheritance tax, and experts say savers – and small-cap investors planning retirement – need to act now.
N/A – sector/economy story, no listed company involved (LSE: N/A) This is a broad economic and personal-finance story rather than one tied to a specific London-listed company, so no exchange ticker such as (AIM: TXP) or (LSE: RRR) applies here. From April 2027, most unspent pension pots left on death will be brought within the scope of inheritance tax, ending decades of treatment as one of the UK's most efficient ways to pass on wealth, according to government estimates highlighted ahead of the Autumn Budget.
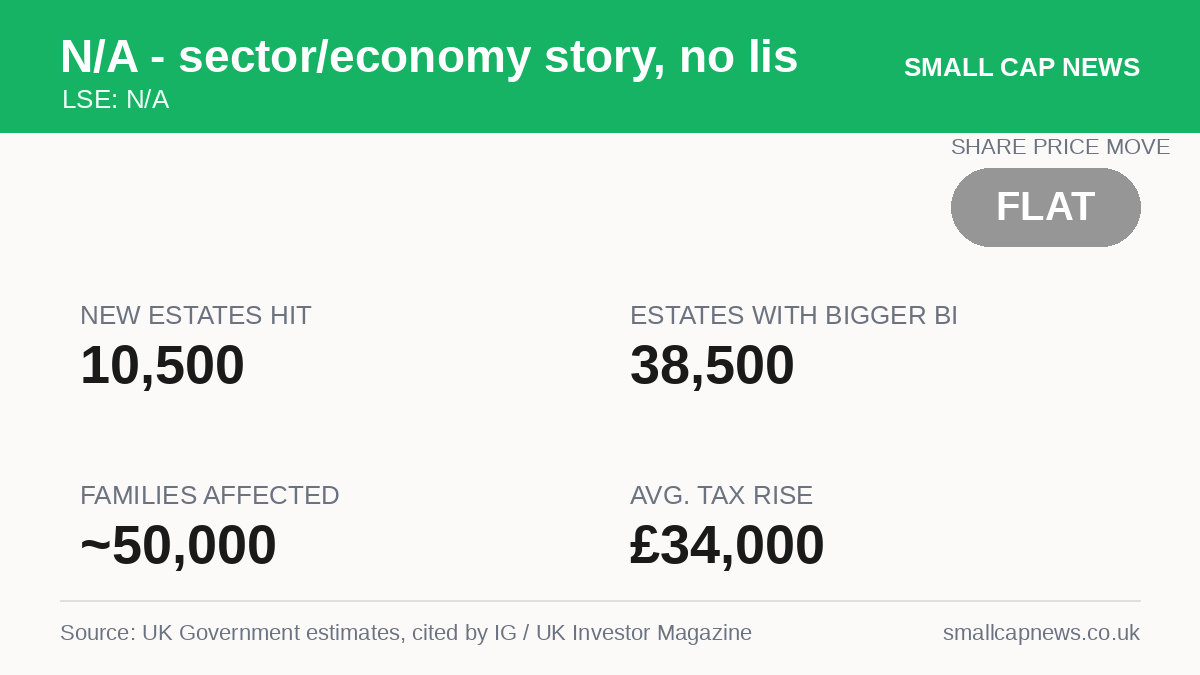
The Treasury expects the change to drag an additional 10,500 estates into inheritance tax for the first time, with a further 38,500 facing bigger bills – roughly 50,000 families in total – and an average increase of about £34,000 per affected estate, prompting advisers to urge savers to review pension arrangements now rather than after the rules bite.
IG investing expert Angeline Ong said the shift, combined with a long freeze on income tax thresholds, means retirement income is increasingly caught in the tax net even before the inheritance tax changes take effect; the Personal Allowance stays at £12,570 and the higher-rate threshold at £50,270 until 2031, so rising pension payments will pull more retirees into higher tax bands over time.
HMRC guidance also warns that where inheritance tax may be due, pension schemes could be told to withhold up to half of a beneficiary's death benefits while liabilities are resolved, adding complexity for families already navigating bereavement, and the technical detail shows that funds inherited before April 2027 but left invested could still fall within the new regime if the recipient later dies after the rules start.
With the Budget approaching, the message from advisers is to get paperwork, beneficiary nominations and investment risk levels in order well before 2027, since younger savers who spot shortfalls or exposure now have far more room to adjust course than those closer to retirement age.
This report is based on N/A – sector/economy story, no listed company involved’s announcement and coverage by UK Investor Magazine. Company announcements can be tracked via London Stock Exchange RNS and Investegate, and the full results calendar is worth watching for the next update.
This article is for general information only and does not constitute investment advice or a recommendation to buy or sell any security. Photo: Vitaly Gariev on Unsplash.
Small Cap News covers London’s junior market – AIM, small-cap and growth companies – with concise, sourced reporting on the results, deals and regulatory news that move share prices. We track the stories private investors actually need, from contract wins and drilling updates to fundraises and half-year figures, straight from the market’s own announcements.